Total Loss Offer Too Low? How to Push Back on Your Insurer
Published on 11/10/2026
Total Loss Offer Too Low? How to Push Back on Your Insurer
The adjuster calls. Your car is a total loss, and here is the number. For many people, that number lands like a second accident. It feels low, it comes fast, and it seems final.
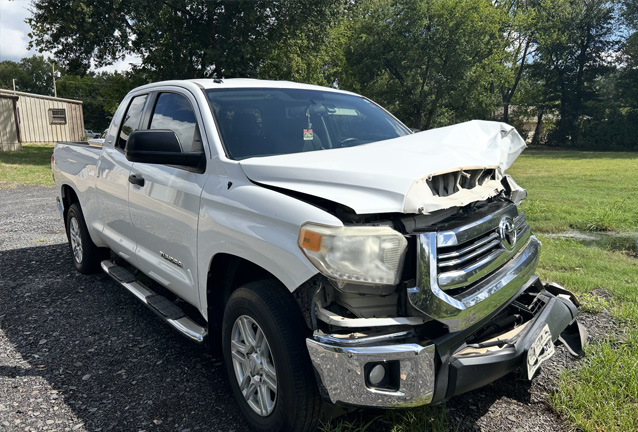
It usually is not final. After more than 30 years in the car business, I can tell you a total loss offer is a starting point based on a report. Reports can be wrong. You have the right to ask questions, and you can often get the number moved with the right evidence.
You are also not alone. CCC Intelligent Solutions reported in March 2026 that total losses hit 23.1% of auto claims, a record high. More drivers are getting this call than ever, and more of them are learning to push back.
How Insurers Decide What Your Totaled Car Is Worth
In many states, the insurer pays the actual cash value (ACV) of your car right before the crash. That is not what you paid, and not what you owe on the loan. It is what a similar car would have sold for in your area that day.
To get there, most insurers use a valuation report. The report pulls "comparable" vehicles, adjusts for mileage, options, and condition, and lands on a number. Then your deductible comes off the top. Check your policy for the exact terms, because rules on taxes, fees, and valuation methods vary by state.
Step 1: Ask for the Full Valuation Report
Do not argue with a number. Argue with the report behind it. Ask your adjuster for the complete valuation, in writing, including every comparable vehicle used. Once you have it, look for these common problems:
• Wrong trim or options. Your car was the upgraded trim with the bigger engine, but the report lists the base model.
• Comps from far away. Comparable cars from a cheaper market several hundred miles off can drag the value down.
• Condition marked too low. A clean, well-kept car rated "fair" loses real money on paper.
• Missing recent work. New tires, a new transmission, or fresh brakes may not show up unless you tell them.
• Mileage mismatches. Make sure your actual odometer reading is the one used.
Step 2: Build Your Own Evidence
Now do your homework. The goal is to show, with documents, what a car like yours really sold for.
Find Your Own Comparables
Look up listings for the same year, make, model, and trim, with similar mileage, as close to home as you can find them. Save screenshots with the date, price, mileage and location. Three to five solid comps make a strong case.
Gather Your Records
Pull together maintenance receipts, recent repair bills, photos of the car before the accident and the original window sticker if you still have it. Anything that proves condition and equipment helps.
Put It in Writing
Send the adjuster a short, polite letter or email. List each error in their report, attach your comps and receipts, and state the value you believe is fair. Calm and organized wins more often than angry and vague.
Step 3: Know Your Options if They Will Not Budge
If the insurer holds firm, you still have moves to consider:
• Appraisal clause. Many auto policies include an appraisal provision. Each side hires an appraiser, and an umpire settles any gap. There is usually a cost, so read your policy first.
• Your state insurance department. Every state has a regulator that takes consumer complaints about claim handling.
• Professional advice. For a large gap, an attorney or public adjuster may be worth a call. This post is general education, not legal or insurance advice.
Step 4: Watch the Clock While You Negotiate
Pushing back takes time, and time costs money when a wrecked car is sitting somewhere. If your car is at a tow yard, tow yard storage fees can keep stacking up every day. Ask your insurer who is paying storage while the claim is open. Also check your policy and claim letters for any deadlines, and keep notes of every call.
Should You Keep the Car Instead?
In many states, you can choose owner-retained salvage. That means the insurer pays you less (the ACV minus your deductible and their salvage value), and you keep the car. We broke down that math in our guide on keeping the car and taking a smaller check.
Here is the key point. If you keep it, the car itself still has value. A wrecked car is not automatically scrap. Before you take a scrap price, read our breakdown of the junk yard quote vs. real value. A fair written offer gives you a real number to compare against what the insurer is deducting for salvage.
Quick Checklist Before You Sign Anything
• Got the full valuation report in writing
• Checked trim, options, mileage, and condition
• Found three to five local comparables
• Sent a written, documented counter
• Asked who pays storage while the claim is open
• Got a written offer on the car if you might keep it
FAQ
Can I negotiate a total loss offer from my insurance company?
Often, yes. Insurers can and do revise offers when you show errors in the valuation or provide better comparable vehicles. Keep it factual and in writing.
Does the insurer have to pay off my car loan?
The insurer pays the car's actual cash value, which may be less than your loan balance. Gap coverage, if you have it, may cover the difference. Check your policy and loan paperwork.
How long do I have to dispute a total loss valuation?
It depends on your policy and your state. Ask your adjuster for any deadlines in writing, and check your policy's appraisal section.
Know Your Number Before You Decide
Whether you settle, push back or keep the car, the smartest move is to know what your car is really worth to a buyer. Get a free, no-pressure offer at trackwala.com and compare it to what the insurer is telling you. Your written TrackWala offer is good for 14 days, so you have time to finish your claim and make the call that is right for you.
Don't Drive It? Sell It!
---
Got a semi, box truck or other heavy truck that is off the road? We buy those too. Get an offer on our truck page: https://arizonawreckedcars.com/sell-heavy-truck/